
We insure our cars and hope we never have an accident.
We insure our homes and hope we never experience a fire, flood or major damage.
But what about our pets?
Pet insurance is something I’ve been thinking about a lot lately, especially after everything we’ve been through with Blaze.
It’s something I’ve been recommending to dog owners for years, but recent events have made me appreciate just how valuable it can be.
And looking back, it’s interesting how much my attitude towards pet insurance has changed over the years.
🎁 Thinking about pet insurance? We’ve got an exclusive offer for 4 WEEKS FREE with Petcover! You’ll find the voucher codes at the bottom of this blog. 🐾 👇
My journey with pet insurance
When I had my first two dogs, Shine and Asta, pet insurance wasn’t something I even considered.
It wasn’t nearly as common or widely discussed as it is today.
That changed when Ember came along.
Nearly 11 years ago, when I got Ember from her breeder, she came with complimentary puppy insurance through Petplan (now Petcover).
When that free insurance period ended, I decided to keep the policy going.
And I’m so glad I did!
Over the years, we’ve claimed for Ember’s arthritis diagnosis and ongoing treatments, and Petcover has consistently been fantastic to deal with.
When Blaze joined our family a few years later, insuring him was an easy decision.
But when Azmin came along, I started questioning whether insuring multiple dogs was really worth the expense. After all, I’d been paying insurance premiums for years without making any major claims.
The $10,000 decision that could have gone very wrong!
As anyone with multiple dogs knows, the costs of pet ownership can add up quickly.
Food, vaccinations, flea and worm treatments, veterinary care, training, equipment… and then insurance premiums on top of everything else.
When Azmin came along, I sat down and worked out how much I could potentially save if I didn’t insure her.
Over ten years, I calculated that I could save approximately $10,000 in insurance premiums.
That’s a lot of money!
I seriously considered putting that money aside instead.
But ultimately, I decided I wasn’t prepared to take the risk.
And thank goodness I made that decision!
By the time Azmin was just nine months old, we’d accumulated over $9,000 in veterinary bills.
Nine months!
Suddenly, that potential $10,000 saving over ten years didn’t seem quite so appealing.
It was a pretty powerful reminder that while you can plan for routine veterinary expenses, you can’t always plan for the unexpected.
And then came Blaze… ❤️
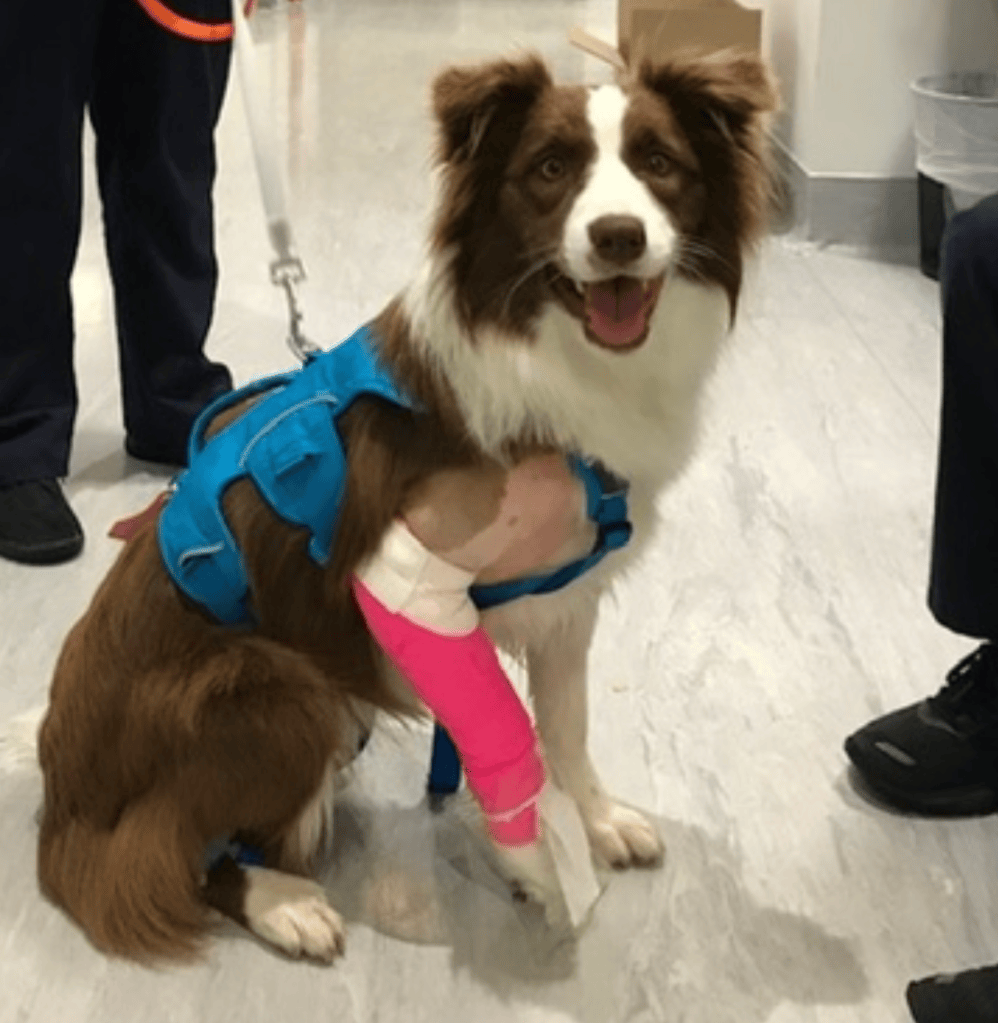
Recently, Blaze had an unexpected accident that led to some serious veterinary visits.
Without going into all the details, his veterinary bills climbed to approximately $10,000 incredibly quickly.
And the scary part?
We hadn’t even reached the stage of treating his injuries yet.
Those costs had largely been for emergency care, examinations, diagnostics and specialist consultations.
Anyone who has had a seriously injured pet will understand just how emotionally overwhelming the experience can be.
You’re worried about your dog.
You’re trying to understand the injuries, treatment options and prognosis.
You’re facing difficult decisions, often without knowing exactly what the outcome will be.
And on top of all that, you’re having to consider the financial implications.
It’s incredibly stressful.
I cannot tell you how grateful I am that Blaze was insured.
Petcover processed our claim and paid out the following day.
Throughout the nearly 11 years I’ve been with them, they’ve consistently been fantastic when it comes to paying our claims.
Having insurance certainly doesn’t take away the emotional stress of having an injured dog, but it can help ease some of the financial pressure when you’re already dealing with so much.

So, is pet insurance really worth it?
That’s a question every pet owner needs to answer for themselves.
And I completely understand why people question it.
Insurance premiums can add up, especially when you have multiple pets.
You could potentially pay thousands of dollars in premiums over your pet’s lifetime and never make a significant claim.
But isn’t that the case with most insurance?
We don’t insure our homes because we’re expecting them to burn down.
We don’t insure our cars because we’re planning to have an accident.
We insure them because we know that sometimes unexpected things happen, and the financial consequences can be significant.
Pet insurance is no different.
Some people prefer to put money aside into a dedicated veterinary savings account, and that can certainly be an option.
But the difficulty is knowing whether you’ll have saved enough when something happens.
If an unexpected veterinary bill arrives when your dog is only nine months old, as happened with Azmin, would you have enough money set aside to cover it?
And what if those bills reach $10,000 or more?
For me, having insurance means knowing that if something happens, I have some financial support available, subject to my policy limits, excesses and conditions.
It doesn’t mean every veterinary expense will be covered, and it certainly doesn’t remove the need to make difficult decisions.
But it can make an enormous difference.
What should you consider when choosing pet insurance?
Not all pet insurance policies are the same, so it’s important to understand what you’re purchasing.
Some things worth looking at include:
- Annual cover limits: How much will your insurer pay towards eligible claims each year?
- Excesses and co-payments: How much of each claim will you need to contribute?
- Accident and illness cover: Does the policy cover both, or accidents only?
- Pre-existing conditions: Are there any existing health issues that won’t be covered?
- Waiting periods: How long after taking out a policy does certain cover begin?
- Ongoing conditions: How are long-term illnesses, such as arthritis, covered?
- Age restrictions: Are there limitations or changes in cover as your pet gets older?
It’s also worth remembering that even with insurance, you may still have substantial out-of-pocket expenses.
For example, with Blaze’s policy, we have a $10,000 cover limit and a 25% contribution towards eligible claims.
That means insurance has been incredibly helpful, but it hasn’t covered all our expenses.
Understanding your policy before you need to claim is really important.
My experience with Petcover
I’ve personally been insuring my dogs with Petcover (previously Petplan) for nearly 11 years.
Over that time, we’ve made claims for various veterinary treatments, including Ember’s arthritis, Azmin’s elbow dysplasia diagnosis and specialist surgery and, most recently, Blaze’s accident.
I’ve consistently found Petcover straightforward to deal with, and they’ve been great when it comes to paying our claims.
In fact, Blaze’s recent claim was paid the very next day!
Of course, that’s my personal experience, and every claim is assessed according to the individual policy and circumstances.
But after nearly 11 years as a customer, I’m happy to recommend them as an insurance provider worth considering.
And I’m now pleased to be partnering with Petcover to offer Shine Pets customers a little something extra!
🎁 Get 4 Weeks FREE Pet Insurance with Petcover!
If you’ve been considering pet insurance, here’s an opportunity to explore your options.
Through our partnership with Petcover, we have two different offers available…
🐶 Puppies & Kittens (8 weeks to 12 months)
Get 4 weeks of complimentary insurance for eligible puppies and kittens.
✅ Code: NZ-SHINE
👉 REDEEM YOUR FREE PUPPY/KITTEN COVER
Click the link, select Redeem Voucher and enter the code above.
🐕 Older Pets (Over 12 months)
Get 4 weeks free when you take out a new paid Petcover insurance policy.
✅ Code: SHINE4WK
For this offer, you’ll need to:
1. Visit Petcover and start a new insurance quote.
2. Complete the quote process and select your preferred cover.
3. Enter SHINE4WK in the promotional code field when prompted.
Terms and conditions, eligibility criteria, waiting periods and policy exclusions apply. The older-pet offer requires a new paid policy. Make sure you read the policy information carefully to understand what is and isn’t covered.
A little disclaimer… 😊
Shine Pets is a Petcover partner, which means if you take out a policy using one of our codes, we receive a small commission.
And after Blaze’s recent adventures, I can assure you that commission will be going straight into his rather expensive veterinary fund! 😂🐾
My final thoughts
Looking back over nearly 11 years of insuring my dogs, I’m incredibly grateful I made the decision to continue Ember’s puppy insurance all those years ago.
I’ve certainly questioned the cost at times, especially with multiple dogs insured.
But after everything we’ve experienced with Azmin and Blaze, I know I’ve made the right decision for our family.
Of course, insurance isn’t for everyone, and everyone’s financial circumstances are different.
But if you’ve been sitting on the fence about insuring your pet, I hope sharing our experiences has given you something to think about.
Because sometimes the question isn’t whether you can afford pet insurance. It’s whether you could afford an unexpected veterinary bill without it.
Hopefully, you’ll never need to make a major claim.
But if the unexpected happens, you’ll be grateful you considered your options.
Give your dogs an extra cuddle from me. ❤️
Tarah
Shine Pets 🐾

